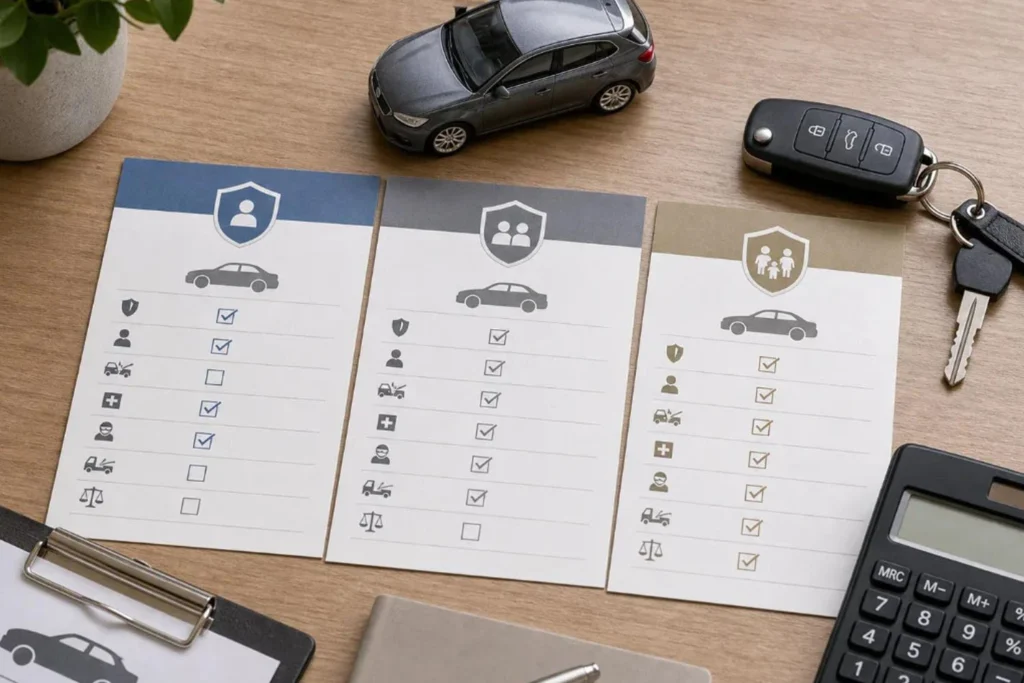
Comparing auto insurance quotes in California is about more than finding the lowest premium. Two quotes may look similar at first but offer different coverage limits, deductibles, exclusions, and payment terms.
To make a meaningful comparison, you need to review what each policy includes and understand how much you may have to pay out of pocket after a covered accident. Looking at these details side by side can help you make a more informed decision based on your vehicle, budget, and coverage needs.
This guide explains how to compare car insurance quotes, which policy details to review, and what California drivers should consider before choosing coverage.
“If you are new to the quoting process, our guide explains what a car insurance quote includes and how it works
1. Compare the Same Coverage Limits
The first step is to make sure you are comparing similar coverage.
An insurance quote with a lower premium may provide lower limits or fewer coverage options than another quote. If the policies are different, comparing only their prices can give you an incomplete picture.
When reviewing quotes, check:
- Bodily injury liability: The limits that apply to injuries you cause to other people in a covered accident.
- Property damage liability: The amount available for covered damage you cause to someone else’s property.
- Collision coverage: Whether damage to your vehicle from a collision is covered, subject to the policy terms and deductible.
- Comprehensive coverage: Whether certain non-collision losses, such as theft or fire, are covered.
- Uninsured or underinsured motorist coverage: Whether this protection is included or available and what limits apply.
Not every quote will include the same types of coverage. Some coverages may be optional, while others may be required by law, a lender, or a leasing agreement.
For a fair comparison, ask each insurer or agent to quote the same coverage types and limits whenever possible. This makes it easier to identify meaningful differences between offers.
2. Review the Deductibles
A deductible is the amount you are responsible for paying toward a covered claim before the applicable insurance coverage pays the remaining covered amount.
For example, imagine two quotes that include comprehensive coverage:
- Quote A has a $500 deductible.
- Quote B has a $1,000 deductible.
If both policies cover the same loss and the claim is large enough, Quote B would generally require you to pay more out of pocket before the insurer pays its covered share.
A higher deductible may reduce the premium, but it also means you need to be prepared to cover more of the cost if you file a claim.
When comparing quotes, record the deductible for each applicable coverage separately. Collision and comprehensive coverage, for example, may have different deductibles.
Ask yourself: If I had to pay this deductible tomorrow, could I afford it?
The lowest premium may not be the most suitable option if its deductible would be difficult for you to manage.
3. Compare the Total Cost, Not Just the Advertised Premium
Insurance prices are often presented as monthly payments, but the payment amount alone does not always tell you the full cost.
Review the following details for each quote:
- Total premium for the policy term.
- Amount due at the start of coverage.
- Monthly or installment payment amounts.
- Installment, billing, or other applicable fees.
- Available discounts and the conditions for keeping them.
- Whether the quoted price is an estimate or a final offer.
For example, one policy might have a lower monthly payment but a different payment schedule or additional fees. Another might require a larger initial payment but have a different total cost over the policy term.
Make sure you compare equivalent time periods. A six-month premium should not be compared directly with a twelve-month premium without adjusting for the difference.
Also, confirm whether a discount has already been applied and whether you meet its eligibility requirements. Do not assume that a quoted discount will continue if the circumstances supporting it change.
4. Read What the Policy Covers—and What It Excludes
A quote provides an estimate of the cost of coverage. It does not necessarily explain every condition, limitation, or exclusion in the complete policy.
Before choosing a policy, review the coverage summary and ask for clarification about anything that is unclear.
Pay attention to:
- Events or losses that are excluded.
- Conditions that must be met for coverage to apply.
- Restrictions involving drivers who may use the vehicle.
- Whether rental reimbursement or roadside assistance is included.
- Any limits that apply to additional benefits.
- The process for reporting an accident and filing a claim.
For example, two quotes may both list comprehensive coverage, but you should still review the applicable deductibles, policy conditions, and exclusions rather than assuming every detail is identical.
If you finance or lease your vehicle, confirm whether your lender or leasing company requires specific coverage.
Never assume that an item is covered simply because it was discussed during the quoting process. Ask for the applicable terms in writing and review the policy documents before purchasing.
5. Evaluate the Insurance Company, Not Just the Price
Price matters, but it is only one part of the decision. You should also understand which insurance company would issue the policy and where to find information about its licensing and consumer complaint history.
California drivers can use resources from the California Department of Insurance to research insurers and compare available information.
Before choosing a company, consider:
- Licensing: Verify that the company is authorized to conduct the relevant insurance business in California.
- Consumer complaint information: Review the department’s published complaint data and understand what the figures measure.
- Policy documents: Make sure you can obtain and understand the terms of the proposed coverage.
- Claims process: Ask how claims are reported and how to contact the company when assistance is needed.
- Customer service: Confirm which channels are available for questions, billing, policy changes, and claims.
You can start with the California Department of Insurance’s automobile insurance resources and its Consumer Complaint Study.
Complaint data is one factor to consider, not a guarantee of how an individual claim will be handled. Review the available information in context and ask questions when necessary.
6. Understand Why Auto Insurance Quotes Differ
Different companies may offer different prices for similar coverage. Insurers evaluate information about the driver, vehicle, requested coverage, and other factors under their applicable rating rules.
Differences between quotes may relate to:
- Driving and claims history.
- Vehicle make, model, year, and use.
- Garaging location.
- Coverage limits and deductibles.
- Eligibility for discounts.
- The insurer’s rating practices and underwriting criteria.
The information provided during the quoting process also matters. Incorrect or incomplete details can make a quote less useful and may affect the final price or eligibility.
Before comparing offers, check that the driver information, vehicle details, address, and requested coverage are accurate and consistent across quotes.
If one price is substantially different from the others, ask the insurer or agent to explain the difference. Check whether the coverage is equivalent and whether the price depends on information that still needs to be verified.
Before requesting quotes, review the information you may need for an auto insurance quote so you can provide consistent details.
7. Use a Quote Comparison Worksheet
A simple comparison table can help you organize the details instead of relying on memory or comparing prices from separate screens.
Use the worksheet below when reviewing two or more offers.
| What to compare | Quote A | Quote B |
|---|---|---|
| Insurance company | ||
| Policy term | ||
| Total premium | ||
| Initial payment | ||
| Payment schedule and fees | ||
| Bodily injury liability limits | ||
| Property damage liability limits | ||
| Collision deductible, if included | ||
| Comprehensive deductible, if included | ||
| Uninsured/underinsured motorist coverage | ||
| Additional benefits | ||
| Important exclusions or restrictions | ||
| Questions still to resolve |
Fill in the information using the written quotes and policy documents. If a detail is missing, ask the insurer or agent rather than assuming it is included.
Once the table is complete, compare the premium, the protection offered, the amount you may need to pay out of pocket, and any policy conditions that matter to you.
The goal is not simply to find the cheapest quote. It is to understand the differences well enough to choose an option that fits your needs and budget.
8. Questions to Ask Before Choosing a Policy
Before accepting a quote, consider asking the insurance company or agent:
- Are the quoted coverage limits and deductibles confirmed?
- Is the premium an estimate, or is any information still pending verification?
- What fees or additional payments may apply?
- Which drivers and vehicles are covered under the proposed policy?
- What important exclusions or restrictions should I understand?
- Which discounts are included, and what eligibility conditions apply?
- How do I report a claim or get help with a policy question?
- When does coverage begin, and what must I do to complete the purchase?
Get clear answers before making a decision. Review the final policy documents and confirm that the coverage matches what you intended to purchase.
9. Where Can California Drivers Start Comparing Auto Insurance Quotes?
Once you know what to compare, the next step is to gather quotes based on accurate information and consistent coverage preferences.
If you are beginning your search, explore our guide to California auto insurance quotes to learn more about starting the process online.
You can also use the California Department of Insurance’s automobile insurance premium comparison resources to review published comparison information. These resources can help with research, but sample rates are not personalized quotes and may not reflect the premium available for your individual circumstances.
When reviewing offers, keep your information consistent, ask questions about unclear terms, and take time to understand the coverage before purchasing a policy.
Frequently Asked Questions
How many auto insurance quotes should I compare in California?
There is no single number that works for every driver. Comparing several quotes can help you understand differences in price and coverage. The important part is to compare similar coverage limits, deductibles, and policy terms.
Why are two car insurance quotes different for the same vehicle?
Insurers may use different rating practices and underwriting criteria. Your driving history, vehicle details, location, requested coverage, and discount eligibility can also affect the price. Check that the information and coverage selections are consistent before drawing conclusions.
Should I choose the cheapest auto insurance quote?
Not automatically. Review the coverage limits, deductibles, exclusions, payment terms, and company information before deciding. A lower premium may come with a higher deductible or different coverage.
Does comparing quotes affect my credit score?
Do not assume that every insurance-related inquiry works the same way. Ask the insurer what information it checks and whether any credit-related information is used in its process. Insurance rating rules and permitted factors vary by state.
Are online auto insurance quotes final prices?
Not always. An online quote may be an estimate based on the information supplied. The final premium and eligibility can depend on verification and the insurer’s requirements. Review the terms and confirm the final price before purchasing.
Final Thoughts: Compare Coverage Before You Choose
Comparing auto insurance quotes is easier when you follow the same checklist for every offer. Review the coverage limits, deductibles, total cost, policy exclusions, payment terms, and insurer information before making a decision.
A lower price can be appealing, but the right comparison helps you understand what you are paying for and what protection the policy provides.
If you are ready to explore your options, start with California auto insurance quotes and review the available information before deciding which coverage may be appropriate for you.
This article is for general educational purposes and is not a substitute for reviewing an insurance policy or obtaining advice about your individual coverage needs.